Kitchen
Kitchen Remodel Financing Options and Tips to Qualify
Kitchen remodel financing options explained in plain terms, plus practical tips to qualify, borrow the right amount and finance kitchen cabinets.
By the Prime Construction team Updated October 13, 2026 6 min read
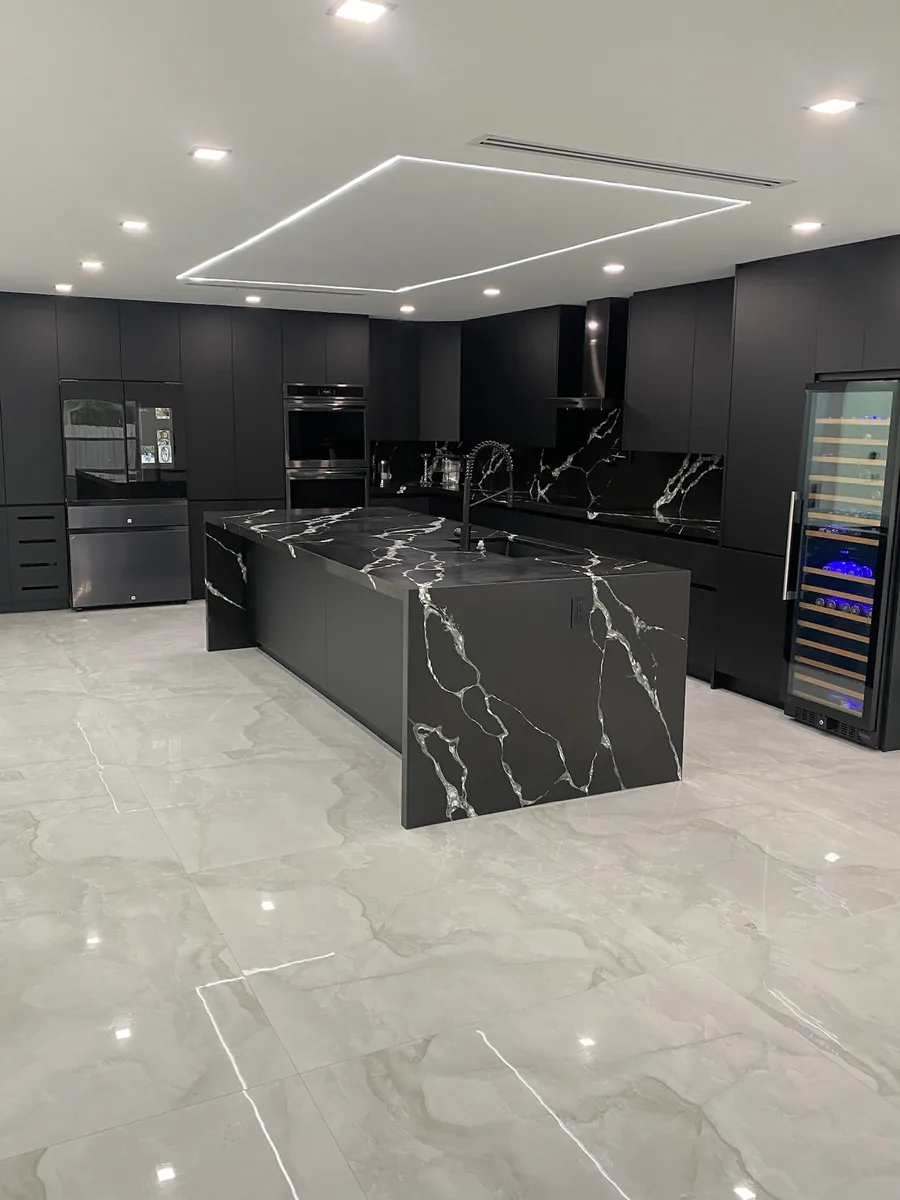
The main kitchen remodel financing options are savings, home equity (a home equity loan, a HELOC or a cash-out refinance), an unsecured personal loan, credit cards or promotional accounts for smaller purchases, and government-backed renovation loans. To qualify for the best terms, check your credit early, know your project cost before you apply, keep new debt to a minimum while you apply, and bring the lender a detailed written estimate. This post gives a short overview of each option, then focuses on the practical steps that make approval easier.
For a deeper dive on specific loan types, see our guides to home equity for a kitchen remodel and kitchen renovation loans.
What a kitchen remodel costs, so you know what to borrow
Typical Orlando-area planning ranges for 2026, installed:
| Kitchen scope | Typical range |
|---|---|
| Cosmetic refresh (same layout: refinish or reface cabinets, new counters, backsplash, sink, lighting) | $15,000 to $35,000 |
| Mid-range full remodel (new stock or semi-custom cabinets, quartz or granite, flooring, appliances) | $35,000 to $75,000 |
| High-end or layout change (custom cabinetry, moved plumbing or walls, premium appliances) | $75,000 to $150,000+ |
| Small kitchen about 70 to 100 sq ft, full remodel | $15,000 to $45,000 |
These vary with size, materials, condition behind the walls and permit scope. The number you finance should be a written estimate after measuring, plus a contingency. Our Orlando kitchen remodel cost guide explains what drives each tier.
Kitchen remodel financing options at a glance
- Savings. No interest, no application. Best if it does not empty your emergency fund.
- Home equity loan. A lump sum secured by your home with fixed payments. Suits one large project with a firm contract price.
- HELOC. A line of credit secured by your home that you draw on as the work progresses. Suits projects paid in stages.
- Cash-out refinance. A new, larger mortgage that pays off the old one and gives you cash. Makes sense mainly if refinancing helps your mortgage too.
- Personal loan. Unsecured, fast to fund, usually more expensive than secured borrowing. Suits smaller kitchens or owners with little equity.
- Credit cards and promotional accounts. Fine for an appliance or fixtures you can pay off quickly. Deferred-interest promotions can charge interest back to the purchase date if a balance remains when the promotion ends.
- Government-backed renovation loans. FHA 203(k), conventional renovation mortgages and FHA Title I property improvement loans. More paperwork, but can help when you are buying a home that needs work or have limited equity.
Financing kitchen cabinets
Cabinets are usually 30 to 40 percent of a full kitchen budget, so “finance kitchen cabinets” is a common search. A few ways to approach it:
- Finance the whole kitchen, not just the boxes. Cabinets are useless without counters, plumbing and installation. One loan sized to the full estimate is simpler to manage than separate accounts for cabinets, countertops and appliances.
- Consider refacing. If your cabinet boxes are sound, cabinet refacing (new doors, drawer fronts, veneer and hardware) typically runs $7,000 to $15,000 for an average kitchen and usually costs 40 to 50 percent less than comparable new cabinets. That can shrink the loan or remove the need for one.
- Watch store accounts. A retailer account may cover the cabinets but not the labor, plumbing or countertop templating, which still need to be paid when the work happens.
- Mind lead times. Cabinets are often ordered weeks before installation, and a deposit is due at ordering. Make sure your financing is in place before that date.
Tips to qualify for kitchen remodel financing
1. Check your credit reports early
Pull your reports a few months before you plan to apply and dispute anything that is wrong. Federal law entitles you to free reports from the nationwide credit bureaus; the official site is listed on the Consumer Financial Protection Bureau website. Lenders set their own requirements, and errors can cost you options.
2. Lower your other debt where you can
Lenders look at how much of your income already goes to debt payments. Paying down a card balance before you apply can help. Avoid opening new accounts, financing a car, or making large purchases on credit while a home equity or renovation loan is in process.
3. Know your equity
For home equity options, the amount you can borrow depends on your home’s value and what you still owe. A recent appraisal or the lender’s valuation sets that number, and every lender sets its own limits. If equity is thin, a personal loan or a smaller first phase may be more realistic.
4. Gather documents before you apply
Typical requests include recent pay stubs, tax returns, bank statements, mortgage statements, homeowners insurance details, and for project loans, a written contractor estimate or contract. Self-employed borrowers are often asked for more income history.
5. Bring a detailed, itemized estimate
A lender is more comfortable with a project that has a clear scope, price and schedule. An itemized estimate (cabinets, countertops, plumbing, electrical, flooring, permits) also helps you avoid borrowing too little. If two estimates are far apart, compare them line by line before you decide how much to borrow.
6. Compare at least three offers
Compare the total cost over the life of the loan, all fees and closing costs, whether the payment can change, and any prepayment penalty. Comparing only monthly payments hides the real cost of a longer term.
7. Ask how money is released
Home equity loans pay you at closing. HELOCs let you draw. Renovation mortgages usually hold funds and release them in draws after inspections. Match the release schedule to the contractor’s payment schedule so work does not stall.
Common financing mistakes on kitchen remodels
- Applying before design is done. If you add an island or move the sink after the loan closes, the extra cost lands somewhere more expensive.
- No contingency. Older Orlando homes can hide galvanized supply lines, outdated wiring or subfloor damage. Plan 10 to 15 percent on top.
- Forgetting the “invisible” costs. Permits, appliance installation, haul-away and temporary kitchen setup all need to be in the budget.
- Signing a loan under pressure. Any offer that must be signed today is a reason to wait until tomorrow.
How phasing can reduce what you borrow
If the full kitchen does not fit the budget, phase it in a sensible order. A common sequence is plumbing, electrical and cabinets first (the parts that are disruptive to redo), then countertops and backsplash, then appliances and lighting. A phased plan only works if the whole design is drawn first, so cabinet sizes, appliance openings and outlet locations are set from day one.
Where Prime Construction fits
Prime Construction does not offer financing or arrange loans. We are a licensed Orlando general contractor and kitchen remodeler, and what we provide is what lenders ask for: a detailed written scope and estimate after we measure, a 3D design rendering so the scope is clear before anything is ordered, and a payment schedule tied to the work. We can also phase a project when that suits your budget.
Planning a kitchen remodel in Orlando?
Start with a real price, then shop the loan. Prime Construction measures your kitchen, prepares a 3D rendering and a detailed written estimate you can take to any lender. Learn about our kitchen remodeling work in Orange, Seminole, Osceola and Lake counties, call (407) 404-3944, or request an estimate.