Kitchen
Kitchen Renovation Loan Guide: Personal, FHA 203(k), Title I
Kitchen renovation loan types explained: personal loans, FHA 203(k), conventional renovation mortgages and FHA Title I loans, and what each requires.
By the Prime Construction team Updated October 13, 2026 5 min read
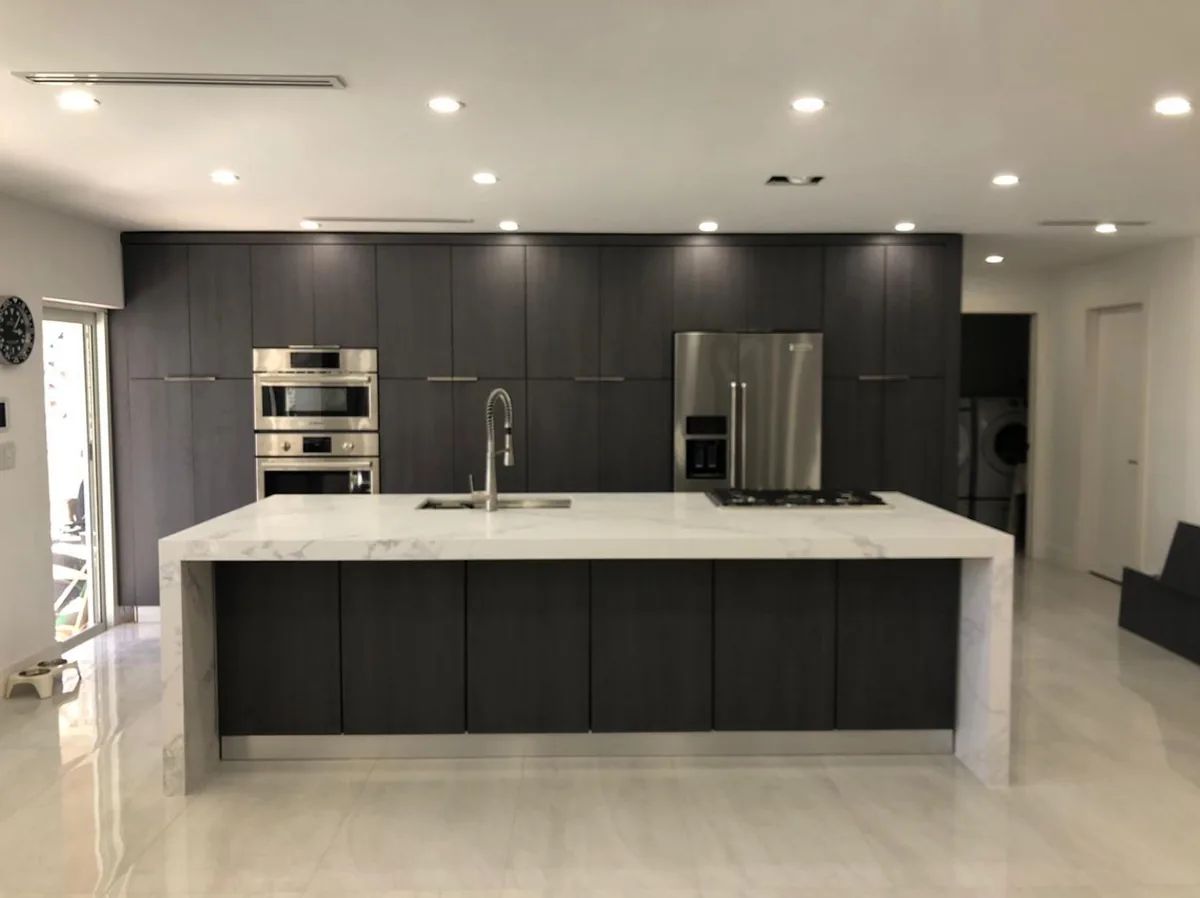
A kitchen renovation loan is any loan used to pay for remodeling work, but the term usually means one of four things: an unsecured personal loan, an FHA 203(k) rehabilitation mortgage, a conventional renovation mortgage, or an FHA Title I property improvement loan. Personal loans are the fastest and simplest. The other three are built specifically for repairs and improvements, come with more rules and paperwork, and can help when you are buying a home that needs work or do not have much equity. This guide explains how each one works and what it asks of you and your contractor.
If you already have equity and want to borrow against it, our HELOC vs home equity loan vs refinance guide covers those options instead.
Kitchen renovation loan types at a glance
| Loan type | What it is | Typical use | Secured? | Paperwork |
|---|---|---|---|---|
| Personal loan | Unsecured installment loan from a bank, credit union or online lender | Smaller kitchens, refreshes, urgent repairs | No | Light |
| FHA 203(k) | FHA-insured mortgage that covers buying or refinancing plus rehabilitation | Buying a fixer-upper or refinancing to remodel | Yes, the mortgage | Heavy |
| Conventional renovation mortgage | Non-FHA mortgage that includes renovation costs, based on the home’s value after improvements | Buying or refinancing with a larger remodel | Yes, the mortgage | Heavy |
| FHA Title I property improvement loan | Private loan insured by HUD for improvements | Owners with limited equity | Above $7,500, per HUD | Moderate |
Rates and terms are not listed because they change and every lender sets its own. Get each offer in writing.
Personal loans for a kitchen renovation
A personal loan is a lump sum you repay in fixed installments. Because it is unsecured, there is no appraisal, no lien on the home and usually no closing in the mortgage sense, so it can fund within days of approval.
Good fit when:
- The project is a cosmetic refresh or small kitchen. In the Orlando area those typically run $15,000 to $35,000 and $15,000 to $45,000 respectively in 2026.
- You have little equity, or you just bought the home.
- A real problem, such as a leak under the sink base, needs fixing now.
Watch for:
- Higher cost than secured borrowing, in most cases.
- Origination fees taken out of the loan amount, which means you may need to borrow slightly more.
- Loan limits that may not cover a mid-range or high-end remodel.
FHA 203(k) loans
HUD describes the 203(k) program as an FHA-insured mortgage that covers the purchase or refinancing of a home and its rehabilitation in one long-term loan. Part of the money pays the seller or your existing mortgage, and the rest is held in escrow and released as the work is done. The home must be at least a year old. HUD’s 203(k) program page has the details.
There are two types:
- Standard 203(k): for major rehabilitation or repairs.
- Limited 203(k): for less expensive repairs and improvements.
A kitchen remodel may fit either, depending on the scope. HUD sets rules on eligible improvements and on how much can be borrowed, and those limits change, so confirm current figures with an FHA-approved lender.
What a 203(k) asks of your contractor:
- A detailed written scope and itemized cost, often reviewed by the lender (and for larger projects, a 203(k) consultant if the lender requires one).
- Licensing and insurance documentation.
- A schedule that works with inspection-based draws. Work is paid in stages after it is inspected, not all up front.
The tradeoff is time. 203(k) loans usually take longer to close than ordinary mortgages, so plan the kitchen design and the loan at the same time.
Conventional renovation mortgages
Conventional (non-FHA) renovation mortgages work on a similar idea: one mortgage that includes the purchase or refinance plus the cost of renovation, often based on what the home is expected to be worth after the work. Lenders offering them set their own eligibility, documentation and draw rules.
They tend to suit:
- Buyers purchasing a home with a dated kitchen who want one loan and one closing.
- Owners refinancing who want to include a larger remodel.
- Projects where the improvements are expected to raise the home’s value enough to support the loan.
Expect the same contractor requirements as a 203(k): a detailed scope, itemized bid, license and insurance, and funds released in draws.
FHA Title I property improvement loans
Title I is a separate HUD program. According to HUD’s Title I program page:
- Private lenders make the loans and HUD insures the lender against loss.
- The loan must fund improvements that substantially protect or improve the basic livability or utility of the property.
- Loans (or combined Title I balances) above $7,500 must be secured by the property.
- The home must have been completed and occupied for at least 90 days before you apply.
- The rate is fixed and negotiated with the lender, and there is no prepayment penalty.
HUD sets a maximum loan amount, and current limits should be confirmed with a lender that offers Title I loans. Title I can help owners who have little equity and want an alternative to unsecured borrowing.
How to choose the right kitchen renovation loan
- Are you buying or refinancing? If yes, a 203(k) or conventional renovation mortgage can fold the kitchen into one loan.
- How big is the project? A $20,000 refresh and a $90,000 layout change call for different tools. See our Orlando kitchen remodel cost guide to place your project in a tier.
- How much equity do you have? Little equity points to a personal loan or Title I. Plenty of equity opens home equity options.
- How fast must the work start? Personal loans fund fastest; renovation mortgages are slowest.
- Can you live with draws and inspections? Renovation mortgages control when money is released. That protects you, but it adds steps.
Mistakes to avoid with renovation loans
- Choosing a contractor who has not worked with draws. Ask how they handle inspection-based payments before you sign.
- Leaving out a contingency. Many renovation programs ask for one, and older Orlando homes can hide plumbing or electrical problems.
- Changing the scope after approval. Changes may need lender approval and can delay draws.
- Skipping the license check. Verify any Florida contractor at myfloridalicense.com. Lenders commonly ask for the license number too.
Where Prime Construction fits
Prime Construction does not offer financing and does not arrange loans. We are a licensed Orlando general contractor (CGC1535686) and kitchen remodeler. For a renovation loan we provide what lenders ask for: a detailed written scope and itemized estimate after an in-home measure, a 3D rendering that pins down the design, license and insurance information, and a payment schedule that can follow the lender’s draw schedule. We pull permits as the licensed contractor, and we can phase a project if you would rather borrow less. If you are weighing savings against a loan, our guide on how to pay for a kitchen remodel covers the cash and phasing side.
Planning a kitchen renovation in Orlando?
A renovation loan moves faster when the scope is clear before you apply. Prime Construction measures, designs and prices your kitchen remodel in writing, and also handles larger home remodeling projects across Orange, Seminole, Osceola and Lake counties. Call (407) 404-3944 or request an estimate.